Short Versus Long Business Loans: Which Fits?
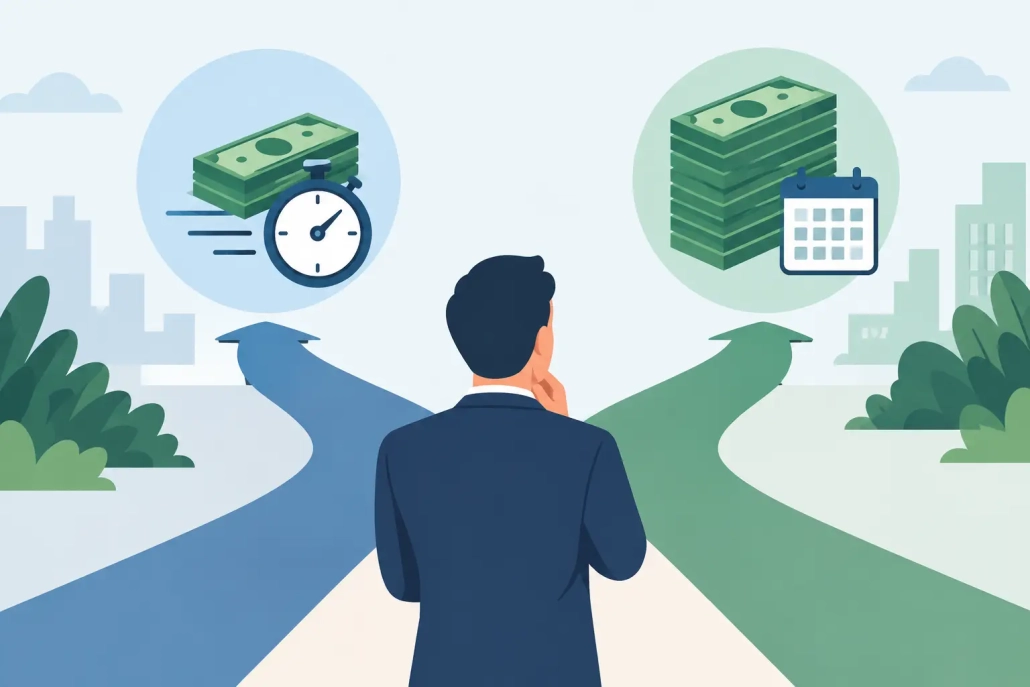
A broken delivery truck, a surprise inventory opportunity, and a planned second location can all require capital. But they should not automatically be financed the same way. When comparing short versus long business loans, the right choice comes down to how quickly you need funds, how soon the investment will produce revenue, and what your business can comfortably repay each month.
A short-term loan can put working capital in your account quickly when operations cannot wait. A long-term loan can offer a more manageable monthly payment for larger investments that will pay off over years. The goal is not simply to get approved. It is to choose financing that solves the problem without creating a new cash flow problem.
Short Versus Long Business Loans at a Glance
Short-term business loans generally have repayment periods ranging from a few months to about 18 months, though terms vary by lender and product. They are often used for immediate operating needs: payroll, materials, repairs, seasonal inventory, marketing pushes, or a temporary cash flow gap.
Long-term business loans usually provide repayment periods of several years. They are designed for larger, longer-lasting investments such as equipment, commercial improvements, expansion, major inventory purchases, or refinancing qualifying business debt.
The biggest difference is not just the timeline. Shorter financing often means faster underwriting and a quicker path to funds, but it can come with more frequent payments and a higher payment amount. Longer financing can spread the cost over more time, which may reduce the regular payment, but approval can require more documentation and the business may pay more total interest over the life of the loan.
When a Short-Term Business Loan Makes Sense
Short-term funding is built for urgency and speed. A restaurant may need to replace a walk-in cooler before the weekend. A trucking company may need a repair to keep a revenue-producing vehicle on the road. A contractor may need materials before starting a confirmed job. In each case, waiting weeks for a traditional bank decision could cost far more than the financing itself.
This option can also work well when you can clearly see how repayment will be supported. If an eCommerce business is buying inventory that should sell within a few months, or a salon is funding a targeted promotion ahead of its busy season, a shorter repayment schedule may align with the expected revenue cycle.
Short-term loans are not ideal simply because they are fast. Frequent daily or weekly payments can pressure a business with inconsistent sales. Before accepting an offer, look at your slowest weeks, not just your strongest month. If the payment only works when every sale goes as planned, the funding structure may be too aggressive.
Common short-term uses
Short-term business financing is often a practical match for immediate working-capital needs, including:
- Covering payroll during a temporary receivables delay
- Purchasing fast-turning inventory or raw materials
- Repairing essential vehicles, equipment, or facilities
- Taking on a profitable contract that requires upfront costs
- Bridging a seasonal sales gap
Speed matters most when the need is tied directly to keeping the doors open or capturing revenue that is already within reach.
When a Long-Term Business Loan Makes Sense
A long-term loan is usually the better fit when the asset or project will generate value over a longer period. Financing a five-year equipment investment with a very short repayment window can put unnecessary pressure on daily cash flow. Matching the financing term to the useful life of the purchase is often a smarter move.
For example, a construction company purchasing equipment, an auto shop adding service bays, or a growing company opening another location may need more capital and more time to repay it. A longer term can preserve cash for labor, inventory, rent, and the other expenses that come with growth.
Long-term financing can also be a good choice for businesses with stable revenue that want predictable payments. Depending on the lender and the borrower’s qualifications, it may offer more favorable pricing than fast short-term capital. However, the approval process can take longer, and lenders may look more closely at credit, time in business, annual revenue, financial statements, and collateral.
A longer term is not automatically cheaper. Lower monthly payments can make a loan easier to manage, but extending repayment can increase the total amount paid over time. Always evaluate both the payment and the full cost of financing.
Compare the Payment Schedule, Not Just the Rate
Many business owners focus first on the advertised rate. Rate matters, but it does not tell the entire story. The payment schedule, fees, term length, and total repayment amount can have just as much impact on your operation.
A short-term offer may have a higher payment because the balance is repaid quickly. That can be acceptable if the capital creates a quick return. A long-term offer may have a lower monthly payment, freeing up operating cash, but the commitment lasts longer.
Ask these practical questions before choosing an offer: How often will payments be withdrawn? What is the total repayment amount? Are there origination or other fees? Can you pay early, and if so, does that reduce the cost? Most importantly, can your business make the payment during a slower month without falling behind on payroll, rent, suppliers, or taxes?
The best financing payment is one your business can make consistently while still having room to operate.
Approval Speed and Qualification Can Be Different
Traditional long-term financing can involve a detailed review and more paperwork. That may work well for an established business planning a major investment months in advance. It is less useful when a repair, purchase order, or payroll deadline is happening now.
Alternative financing options can offer a more accessible route for businesses that need speed or have imperfect credit. Business revenue, operating history, and the purpose of the funds may carry meaningful weight in the decision. This is especially relevant for operators in transportation, restaurants, construction, retail, and other industries where cash flow moves quickly and unexpected expenses are part of the job.
Credit challenges do not always end the conversation. A prior bankruptcy or lower credit score may limit certain options, but businesses with proven sales and a clear need for capital may still have financing paths available. The key is to provide accurate information about monthly revenue, time in business, and existing obligations so the offers you receive are realistic.
Match the Loan Term to the Business Need
A useful rule is simple: use short-term capital for short-term needs and long-term capital for long-term assets. It is not a hard rule, but it is a strong starting point.
If you are buying supplies that will turn into sales within 60 to 90 days, short-term financing may fit the cycle. If you are purchasing equipment that should support revenue for five years, a longer repayment period may make more sense. For recurring flexibility rather than one large expense, a business line of credit may be worth considering instead of either type of term loan.
There are exceptions. A highly profitable company may choose short-term funding for a long-lasting asset if it wants to eliminate debt quickly. A business with uneven seasonal revenue may prefer a longer term for a relatively modest expense to keep payments manageable. Your sales pattern, margins, existing debt, and timing all matter.
Choose Funding That Keeps You Moving
The decision between short versus long business loans is really a decision about timing and cash flow. Fast capital can protect a business when an urgent expense or revenue opportunity cannot wait. Longer financing can make major investments more sustainable by spreading payments across the period when those investments are producing returns.
If you have an immediate need, start by identifying the exact amount required and the revenue that will support repayment. Then compare offers based on payment frequency, total cost, funding speed, and fit for your business goals. Green Sea Funding helps established businesses explore working-capital options built for real operational demands. Apply now, choose the offer that fits, and keep your business ready for what comes next.

Leave a Reply
Want to join the discussion?Feel free to contribute!