Business Line Versus Credit Card: Which Fits?
A vendor bill is due Friday. Your top technician needs a replacement tool. Inventory is moving faster than expected, but the cash from recent sales has not landed yet. In moments like these, choosing a business line versus credit card can shape how much flexibility your company has and what that flexibility costs.
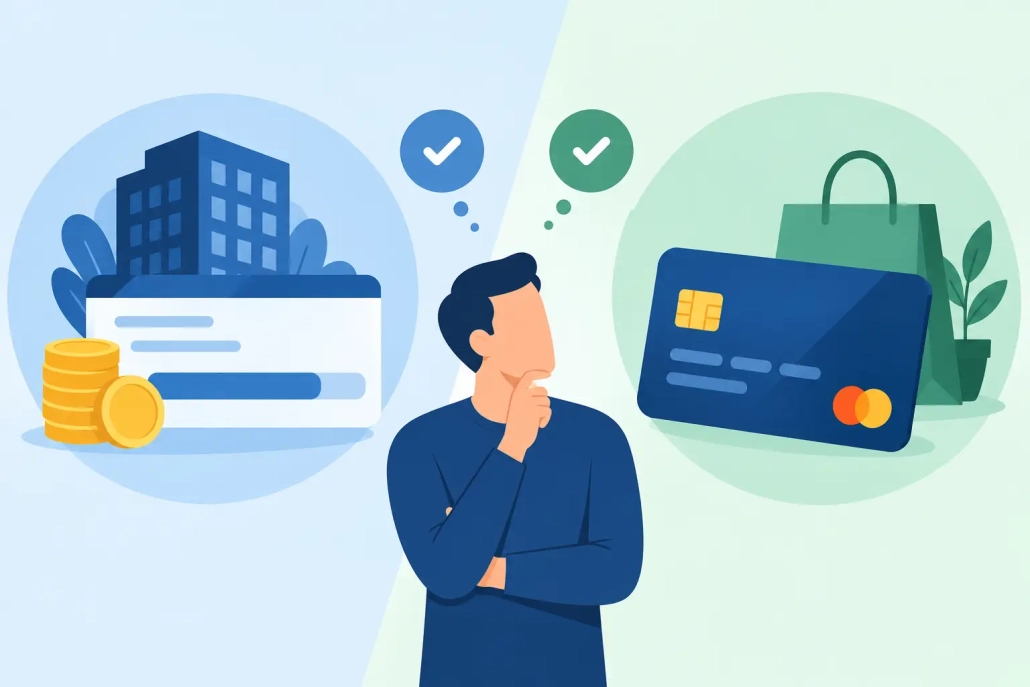
Both options can help cover short-term business expenses. They work differently, though. A business line of credit is usually built for larger working-capital gaps and repeated draws. A business credit card is often better for everyday purchases, supplier payments, travel, and expenses you can repay quickly.
The right choice depends on the purpose of the funds, how fast you expect revenue to come in, and whether you need access to capital beyond a typical card limit.
Business Line Versus Credit Card at a Glance
| Feature | Business Line of Credit | Business Credit Card | |—|—|—| | Primary use | Working capital and operating expenses | Routine purchases and short-term expenses | | Access to funds | Draw funds as needed up to an approved limit | Charge purchases up to a card limit | | Interest | Usually charged only on the amount drawn | May be avoided if the full balance is paid during the grace period | | Repayment | Often weekly or monthly, depending on terms | Monthly minimum payment, with payment flexibility | | Typical funding capacity | Can support larger cash-flow needs | Often lower limits, depending on the issuer and business profile | | Rewards | Less common | May include cash back, travel rewards, or purchase protections |
A line of credit is not automatically better because it may offer more capital. A credit card is not automatically cheaper because a promotional rate or rewards program can look attractive. The useful question is whether the repayment structure matches the way your business earns revenue.
When a Business Line of Credit Makes Sense
A business line of credit gives you access to a set amount of capital that you can draw from when needed. If your company is approved for a $100,000 line and uses $25,000, you generally pay financing costs on the $25,000 draw, not the full $100,000.
This structure can work well for businesses with regular but uneven cash flow. A construction company may need to cover labor and material costs before a customer payment arrives. A restaurant may need extra inventory before a busy holiday weekend. A trucking company may need repairs, fuel, or insurance payments while waiting on invoices.
The main advantage is control. You can use the funds, repay them, and potentially draw again without applying for a new loan every time a short-term need appears. That can be valuable when opportunities and expenses do not follow a neat monthly schedule.
A line of credit can also be a stronger fit when the expense is too large for a card or when a supplier will not accept a card payment. Payroll, rent, emergency repairs, inventory orders, and operating costs may require direct access to cash rather than a charge transaction.
Still, read the terms closely. Some lines have draw fees, maintenance fees, minimum draw requirements, or fixed repayment schedules for each draw. A revolving line is only useful when you know the cost of using it and can plan for the payment schedule.
Use a line for predictable cash-flow gaps
A line of credit is often most effective when you can point to a clear repayment source. For example, you draw funds to purchase inventory that typically sells within 45 days, or to cover payroll while a confirmed customer invoice is expected next month.
It becomes riskier when it is used to cover a long-running loss with no plan for recovery. Financing can buy time, but it cannot fix a pricing problem, declining margins, or a recurring expense that your revenue cannot support.
When a Business Credit Card Makes Sense
A business credit card can be a practical tool for day-to-day spending. It is especially useful for software subscriptions, fuel, office supplies, online advertising, travel, small equipment purchases, and vendor payments that accept cards.
Cards can offer convenience that a line of credit does not. Employees can receive authorized cards with spending controls. Owners can separate company expenses from personal purchases. Monthly statements can also make bookkeeping and expense tracking easier.
If you pay the statement balance in full during the grace period, you may avoid interest on purchases. That makes a card a strong option for expenses your business can repay within the billing cycle. Rewards may add value, but they should never be the reason to carry an expensive balance.
The downside appears when a balance stays on the card month after month. Credit card annual percentage rates can be high, and minimum payments can make repayment take far longer than expected. A card limit can also be reduced or become unavailable at an inconvenient time, particularly if your utilization rises or business conditions change.
Cash advances deserve extra caution. They may carry higher rates, fees, and no grace period. A business owner who needs cash in an operating account is usually better served by comparing working-capital options than relying on a card cash advance.
Use a card for short, trackable expenses
A credit card works best when the purchase is specific, the amount is manageable, and the payoff period is short. Charging $3,000 in supplies that will support revenue this month is very different from putting three months of payroll on a card because cash is consistently short.
For many businesses, the card is an operating tool, not a long-term financing plan.
Compare Cost Beyond the Interest Rate
When weighing a business line versus credit card, do not compare only the advertised rate. Compare the total cost and the way payments affect your cash flow.
A card may have a high APR but cost little if you pay it off before interest accrues. A line may have a lower rate but include fees or scheduled payments that begin immediately after you draw funds. Neither is automatically the lower-cost option without looking at the actual amount borrowed, the expected repayment date, and all applicable fees.
Ask these practical questions before moving forward:
- How much capital do I actually need?
- Will I need cash, or am I paying a merchant that accepts cards?
- When will the business generate the revenue to repay this balance?
- Is the payment schedule weekly, monthly, or tied to the billing cycle?
- Are there draw fees, annual fees, late fees, prepayment rules, or cash advance charges?
A financing decision should support operations, not create a payment that strains the business during its next slow period.
Qualification Can Look Different for Each Option
Traditional business credit cards may rely heavily on the owner’s personal credit profile, particularly for newer businesses. Many issuers require a personal guarantee, meaning the owner may be personally responsible if the business does not repay the balance.
Business lines of credit can also require personal guarantees, and qualification standards vary widely. Lenders may evaluate time in business, monthly revenue, bank activity, existing debt, industry, and credit history. Established companies with steady sales may have more financing choices than businesses without a proven revenue record.
For owners with imperfect credit, the application process matters. A lender that considers business performance alongside credit history may provide options that a traditional bank or major card issuer does not. That does not mean every offer is right. It means you should compare repayment terms, funding amount, speed, and total cost before accepting.
You May Need Both
This is not always an either-or decision. A business credit card and a line of credit can serve different jobs inside the same company.
A salon might use a card for supplies, booking software, and small marketing purchases while keeping a line available for a larger buildout, seasonal payroll pressure, or equipment repair. An eCommerce business may charge shipping and advertising expenses to a card for easy tracking, then draw on a line to place a larger inventory order ahead of a sales season.
The key is setting boundaries. Decide what belongs on the card, what justifies a line draw, and what expenses should not be financed at all. That discipline can prevent short-term tools from becoming permanent debt.
Choose the Tool That Matches the Job
Use a business credit card when speed at checkout, expense management, and short repayment periods matter most. Consider a business line of credit when you need flexible access to cash for larger operating expenses or recurring cash-flow gaps tied to expected revenue.
If payroll, inventory, repairs, or a growth opportunity cannot wait, Green Sea Funding can help established business owners review working-capital options built around their needs. Apply with a clear purpose, know your repayment source, and choose financing that keeps your operation moving forward.

Leave a Reply
Want to join the discussion?Feel free to contribute!