How Revenue Based Financing Works for Businesses
A restaurant has a busy weekend ahead but needs inventory before Friday. A trucking company lands a new route but must repair a truck before it can run it. A contractor has signed work on the books but needs payroll covered before the next invoice clears. In situations like these, understanding how revenue based financing works can help business owners decide whether fast capital fits the job.
Revenue-based financing is designed around the revenue your business already generates. Rather than relying only on collateral, a long credit history, or a bank-style approval process, a provider looks closely at your sales performance and ability to produce future revenue. That can make it a practical option for established businesses that need working capital quickly.
How revenue based financing works
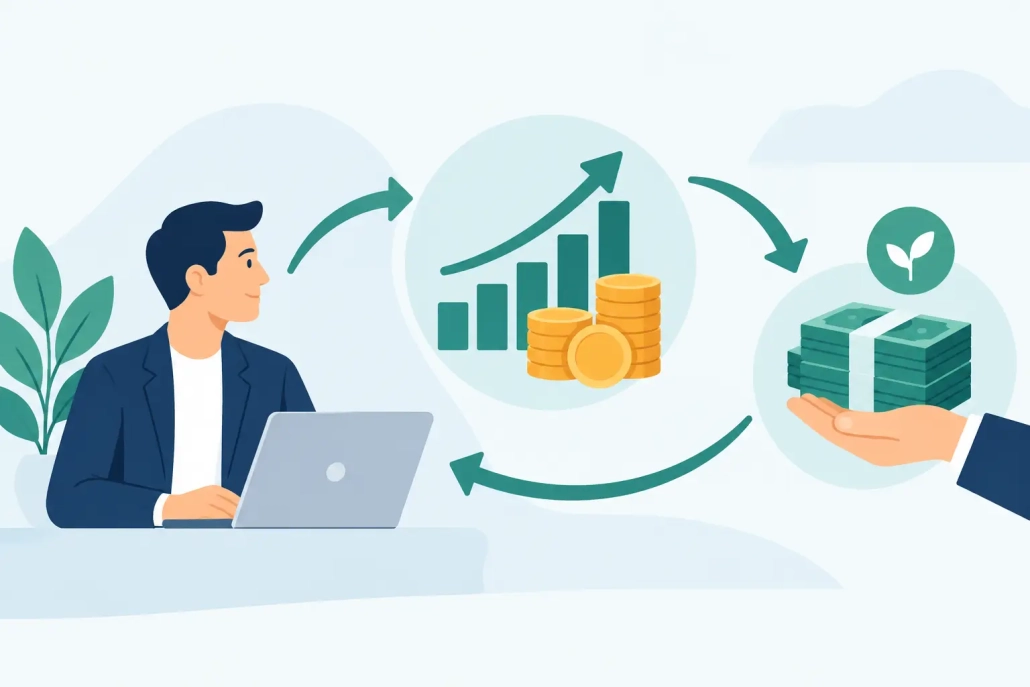
With revenue-based financing, a business receives a lump sum of capital and agrees to repay a set amount from future business revenue. The amount you receive may be used for operating needs such as inventory, equipment repairs, marketing, payroll, seasonal expenses, or expansion.
The provider reviews factors such as average monthly revenue, time in business, recent bank activity, industry, and overall financial profile. Credit can matter, but revenue and operating history often carry significant weight. That is why this type of financing may be available to some owners who do not qualify for a traditional bank loan or who have dealt with credit challenges in the past.
Once approved, you review the offer, including the funding amount, total payback amount, payment method, and expected payment schedule. If you accept, funds can often be deposited quickly, sometimes as soon as the same day after approval.
The repayment amount is agreed upfront
Revenue-based financing is commonly priced with a factor rate rather than an annual percentage rate. For example, if a business receives $50,000 with a 1.25 factor rate, the total amount owed is $62,500. The $12,500 difference represents the financing cost.
That does not automatically tell you whether the offer is affordable. You also need to know how frequently payments are taken, how the payment amount is calculated, and how the repayment timeline fits your cash flow. A lower-looking factor rate can still create pressure if the payment frequency is aggressive for your business.
Payments may move with sales, but contracts vary
The phrase “revenue-based” can describe more than one repayment structure. In a true percentage-of-sales arrangement, the provider receives an agreed percentage of your future sales. When sales are strong, payments may be larger. When sales slow down, payments may decrease.
Other products tied to business revenue use fixed daily or weekly ACH withdrawals. These payments may be based on your historical sales, but they do not necessarily adjust automatically each time revenue changes. Some agreements include reconciliation provisions that may allow a payment adjustment if sales fall below expectations. Others may not.
This distinction matters. Before accepting an offer, ask whether repayment is a fixed withdrawal or a percentage of actual sales, whether there is a reconciliation process, and what documentation is required to request an adjustment. Read the agreement carefully rather than assuming every revenue-based product works the same way.
A simple revenue-based financing example
Assume an auto repair shop averages $80,000 in monthly sales. A busy season is approaching, but two lifts need repairs and the owner wants to stock common parts before demand picks up. The shop receives $40,000 in financing with a total payback of $50,000.
If the agreement collects 10% of daily card sales, the repayment amount may rise and fall with business volume. A $5,000 sales day could produce a $500 payment, while a slower $2,000 day could produce a $200 payment. The total amount owed remains $50,000, but the time required to repay it depends on sales.
If the agreement instead requires a fixed weekday withdrawal, the shop knows the expected payment amount but must plan around it. That structure can work well for predictable revenue. It can be harder to manage if the business has sharp seasonal dips, delayed customer payments, weather disruptions, or unexpected repair bills.
For either structure, the owner should calculate the impact on weekly cash flow before accepting funds. Financing should support the business, not leave too little room for labor, rent, fuel, inventory, taxes, and other essential expenses.
When this financing can make sense
Revenue-based financing can be useful when capital has a clear purpose and a realistic return. A salon may use funds to add stations before a high-demand period. An eCommerce seller may buy proven inventory ahead of the holidays. A transportation company may repair a revenue-producing vehicle quickly instead of losing booked jobs.
It can also make sense when speed matters more than a long bank underwriting process. If waiting several weeks would mean missing a contract, losing a supplier discount, or falling behind on a time-sensitive operating need, faster access to capital has real value.
For many owners, the biggest benefit is flexibility in qualification. A business with consistent sales may have options even if the owner has imperfect credit, limited collateral, or a previous bankruptcy. Approval is never guaranteed, and each provider has its own requirements, but business performance can open doors that conventional lending may keep closed.
When to be careful
Fast funding is not the same as cheap funding. Revenue-based financing may cost more than a bank loan or SBA loan, particularly when the repayment term is short. It is generally better suited to short-term working-capital needs, opportunities with measurable returns, and businesses that can handle frequent payments.
Be cautious about using it to cover an ongoing loss with no plan to improve revenue. If payroll, rent, and vendor bills are consistently higher than incoming sales, adding another payment may deepen the problem. In that case, the business may need a broader cash-flow plan, lower fixed expenses, renegotiated vendor terms, or a longer-term financing option.
You should also avoid taking multiple advances without fully understanding your total obligations. Stacking financing can create several daily or weekly withdrawals at once. That may reduce the cash available to operate and make it difficult to qualify for future funding on better terms.
Questions to ask before choosing an offer
Before you choose an offer, get clear answers on the funding amount, total payback, payment frequency, estimated repayment timeline, and any fees. Ask whether there are prepayment options or savings, whether payments can be reconciled during a slowdown, and whether the provider requires a personal guarantee, lien, or other security interest.
It is also smart to compare the offer against alternatives. A business line of credit may be better for recurring expenses. A term loan may fit a larger purchase with a longer useful life. An SBA loan can be worth considering when the business has time for a more detailed application and wants potentially lower-cost long-term capital. The right product depends on urgency, revenue consistency, credit profile, and what the funds will accomplish.
Have recent business bank statements, monthly sales figures, and a clear use of funds ready before applying. A straightforward application and accurate information can help move the review process faster and help you evaluate offers with confidence.
The best financing decision starts with one practical question: will this capital help the business generate or protect more cash than it costs? If the answer is clear and the payment fits your real sales cycle, revenue-based financing can provide a fast path from an immediate need to forward momentum.

Leave a Reply
Want to join the discussion?Feel free to contribute!