Seasonal Line of Credit for Predictable Cash Flow
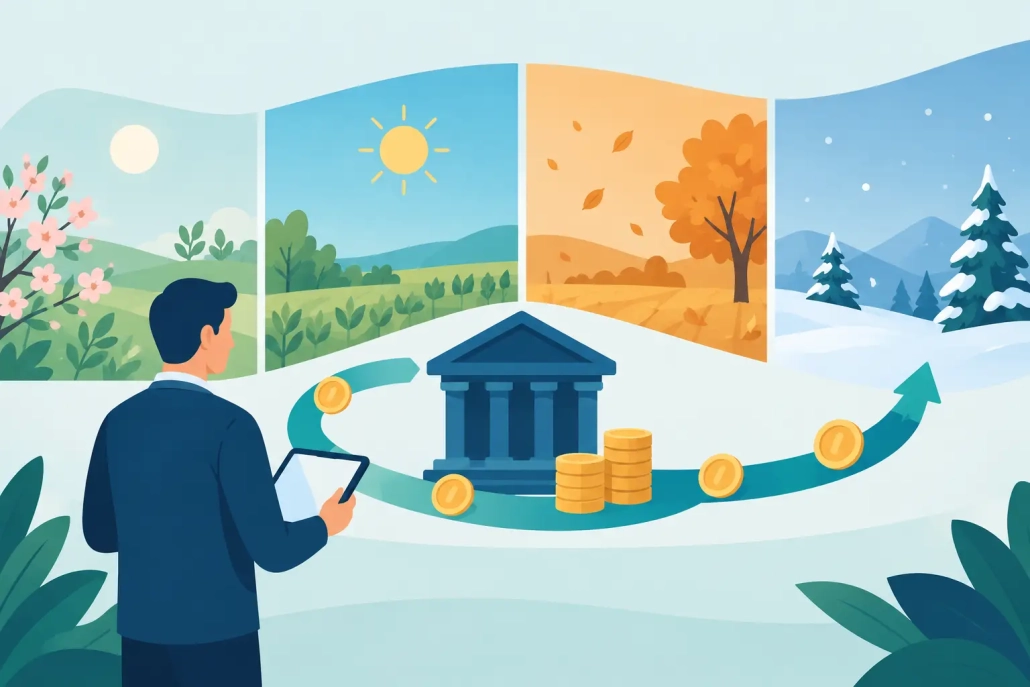
A busy season can create a cash-flow problem before it creates a revenue win. Your restaurant needs food orders before the summer crowd arrives. A contractor needs materials and payroll before a major project reaches its first payment milestone. An online retailer needs inventory well ahead of holiday sales. A seasonal line of credit gives an established business access to working capital when expenses hit first and customer payments come later.
Unlike a one-time loan, a line of credit is designed for repeat business needs. You draw funds up to an approved limit, use what the business needs, and repay based on the financing terms. That can make it a practical option when sales follow a predictable pattern but monthly expenses do not.
Why Seasonal Businesses Need Flexible Capital
Seasonality is not limited to businesses that close for part of the year. It affects companies in nearly every industry. A landscaping company may have a packed spring and summer. A trucking company may see higher demand around agricultural harvests or holiday shipping. Auto repair shops can face a rush before road-trip season and winter weather. Salons, bars, eCommerce sellers, and marketing agencies often experience revenue spikes around events, holidays, or campaign cycles.
The challenge is timing. Inventory suppliers, employees, fuel providers, equipment repair shops, and landlords expect payment on their schedules. Customers may pay after delivery, after an invoice is approved, or after a project phase is complete. Even a profitable business can feel pressure in the gap between spending money and collecting it.
A seasonal line of credit helps bridge that gap without forcing an owner to borrow a large lump sum months before it is needed. It can provide a financial cushion for planned demand, unexpected opportunities, or short-term revenue dips.
How a Seasonal Line of Credit Works
A lender or financing provider approves your business for a maximum credit limit. For example, if your available limit is $75,000, you may draw $20,000 to purchase inventory in September, then access additional funds later if your business remains within the available limit and terms.
You generally pay financing costs only on the amount you draw, not the entire approved limit. After repayment, the available credit may replenish, depending on the product structure. That revolving access is the major difference between a line of credit and a standard term loan, where you receive one lump sum and make scheduled payments until the balance is paid off.
The terms matter. Some lines have weekly or monthly payments. Some require a periodic payoff or have draw fees, maintenance fees, or other costs. Fast funding can be valuable, but business owners should review the repayment schedule and total cost before accepting an offer. The right structure should support your cash cycle, not create a payment that strains it.
Smart Ways to Use Seasonal Credit
The best use of a credit line is tied to a clear business purpose and a realistic repayment plan. If the expected revenue is seasonal, the financing should help the business generate, protect, or accelerate that revenue.
A retailer may use credit to place a larger order before the holiday rush, avoiding stockouts on proven products. A construction company may cover payroll and material deposits while waiting for a draw payment from a customer. A restaurant may pay for inventory, temporary staff, and repairs before its high-traffic season. A trucking operator may use working capital for fuel, tires, maintenance, or insurance costs before a surge in contracted loads.
It can also help a business respond quickly when an opportunity appears. A supplier discount, a last-minute commercial project, or a sudden equipment repair may not wait for a bank’s long underwriting timeline. Having approved capital available can give an owner more control over decisions that affect revenue.
That said, a line of credit is usually not the best tool for a long-term purchase that will take years to produce a return. Major equipment, a building renovation, or a permanent expansion may fit better with a business term loan, equipment financing, or an SBA loan. Matching the financing term to the life of the asset can reduce pressure on monthly cash flow.
Estimate the Amount Before You Apply
A credit limit should be based on the gap your business actually needs to cover, not simply the largest amount available. Start with your busiest upcoming period and list the costs that must be paid before revenue arrives. Include inventory, payroll, supplier deposits, marketing, fuel, freight, repairs, rent, and taxes.
Then compare those expenses with the customer payments you expect during the same period. Look closely at timing, not just total sales. A business can show strong projected revenue and still run short if invoices are paid 30 or 60 days after the work is completed.
For example, a contractor expecting $150,000 in spring project revenue may need $35,000 for labor and materials before the first customer draw is received. A credit line sized near that temporary gap may be more useful than taking on a much larger balance with no defined use.
Keep a margin for surprises, but avoid treating available credit as extra profit. Every draw creates a repayment obligation. The goal is to keep operations moving while preserving enough cash to handle normal business expenses.
What Lenders May Review
Qualification standards vary, especially between banks and alternative business-financing providers. Traditional lenders may place substantial weight on personal credit, time in business, financial statements, collateral, and detailed cash-flow records. Alternative financing options may focus more heavily on recent business revenue, operating history, and the ability to support payments.
Most providers will want to understand how long you have been operating, your average monthly sales, recent bank activity, existing business debt, and why you need capital. A business with consistent deposits and a clear seasonal pattern is often easier to evaluate than one with unexplained revenue swings.
Credit challenges do not always end the conversation. Owners with lower credit scores or a past bankruptcy may still have financing options if their business has established revenue and a workable repayment profile. However, lower-risk applicants may qualify for more favorable rates and terms, so it is worth improving business finances where possible before applying.
Have recent business bank statements ready, along with basic details on monthly revenue and current obligations. Fast applications move faster when the numbers are organized and accurate.
Compare the Offer Beyond the Credit Limit
A large limit can look appealing, but it is only one part of the offer. Review the payment frequency, financing rate or factor, fees, draw requirements, repayment flexibility, and whether the line can be used repeatedly after repayment. Ask how quickly funds can be available after approval and whether there are restrictions on inventory, payroll, or other working-capital uses.
Also consider your revenue pattern. A weekly repayment may work for a business with daily card sales, while an invoice-based company with longer customer payment cycles may need terms that better align with collections. There is no single best option for every seasonal business.
Green Sea Funding helps established business owners compare working-capital options built around revenue, operating needs, and timing. If your peak season is approaching, it is often better to explore funding before inventory is depleted, payroll is due, or a repair has already interrupted operations.
Use Credit to Prepare, Not Just React
The strongest time to arrange a seasonal line of credit is usually before the pressure starts. When sales are steady, bank deposits are clear, and there is time to compare offers, you can make a more deliberate financing decision. Waiting until a supplier has put an order on hold can limit your choices.
A well-used credit line is not a substitute for profitable operations. It is a tool that helps a healthy business buy, build, staff, and deliver at the right moment. Plan for the season ahead, borrow with a specific purpose, and let the capital support the revenue you already know your business can earn.

Leave a Reply
Want to join the discussion?Feel free to contribute!